Car finance: what consumers want
Consumers want to be able to trust their car dealer and be confident they’re getting a fair car finance deal
Consumer Voice reveals what car finance customers want from their dealer as lenders wait to see if they will be forced to compensate people who have been mis-sold car loans.
Trust and transparency are important to people arranging car finance. In fact, the message we’re hearing loud and clear is that you want to be confident your dealer has no conflicts of interest and you want to understand the total amounts payable to help you compare offers.
Preferences about how deals are presented depends on different shopping habits: around half of people we spoke to said they want their dealership to offer a choice of deals for them to consider and around half say they simply want their dealership to offer the best deal available from their panel of lenders.
We surveyed 2,042 people who took out at least one car finance loan before 28 January 2021. Most were unaware that their dealer could be receiving commission – only 21% said they were aware of this.
Alex Neill, co-founder of Consumer Voice, said:
‘Our research shows that people want to be able to trust their car dealer to offer them a good deal. So, if a dealer does have a conflict of interest, like taking a commission from a lender, it is plainly obvious consumers expect this to be declared.
‘Car finance customers need better information and clarity to give them confidence they’re getting impartial advice before signing up to deals.’
Car finance lenders were told last week by the regulator they could be forced to contact customers who have been mis-sold car loans to ‘offer appropriate compensation.’
The regulator launched an investigation last year into discretionary commission arrangements on car loans – this is where lenders agreed to pay dealers a higher commission if they arrange for the car buyer to pay a higher rate of interest on their loan.
The Financial Conduct Authority banned this practice in January 2021 but consumers have yet to be compensated for being over charged. In April, the Supreme Court will decide whether the use of all undisclosed ‘secret’ commissions – not just discretionary commissions – are unlawful.
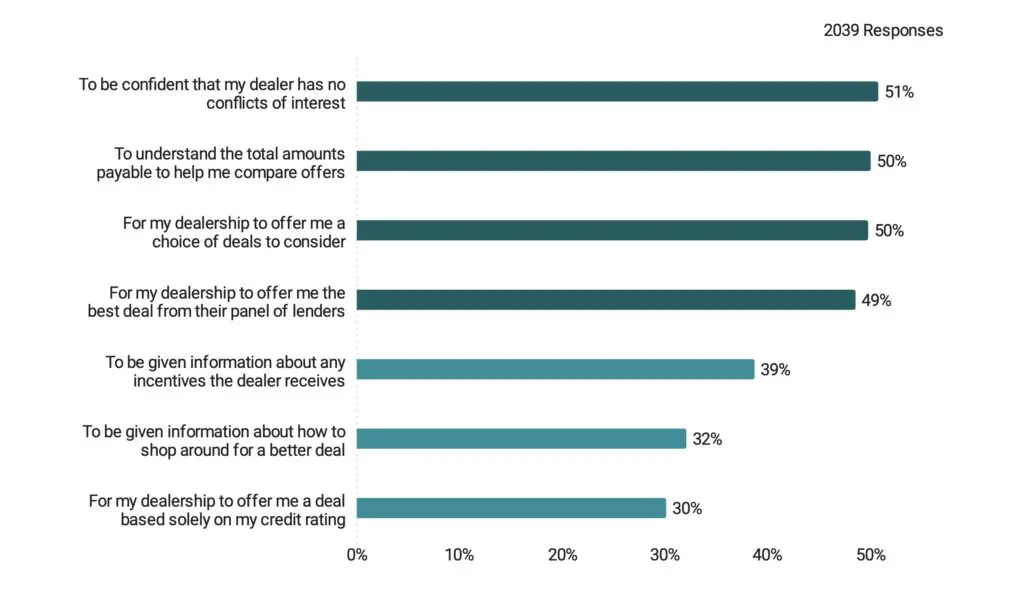
We asked car finance customers to select the three most important things that would help them arrange finance through a car dealership
6 in 10 car buyers trust dealers for competitive loans
Trust is important. More than six in ten (65%) of car finance customers who took out loans before the ban on discretionary commission had trusted their dealer to offer them the best deal. Only 16% of people said they don’t trust them to do this.
The situation hasn’t changed for more recent car finance customers. Research we carried out with car buyers who took out finance deals in the past four years found that 67% said they trusted their car dealer to offer them a competitive finance loan based on their needs – for instance, a loan with monthly payments they can easily afford.
Car finance customers say they want to be confident that their dealer doesn’t have any conflicts of interest – with 51% of people selecting this in their top three priorities in our latest survey. It was as important as having better information to help them compare or be confident they are getting the best deal for them.
This is critical given that only 4% of finance customers say they researched other options before negotiating a better price with their dealer. And people are unfamiliar with the market – most people (68%) had only taken out one car finance loan between 1 April 2014 and 28 January 2021, and 65% haven’t taken out car finance again since January 2021.
Car buyers demand transparency on dealers commissions and fees
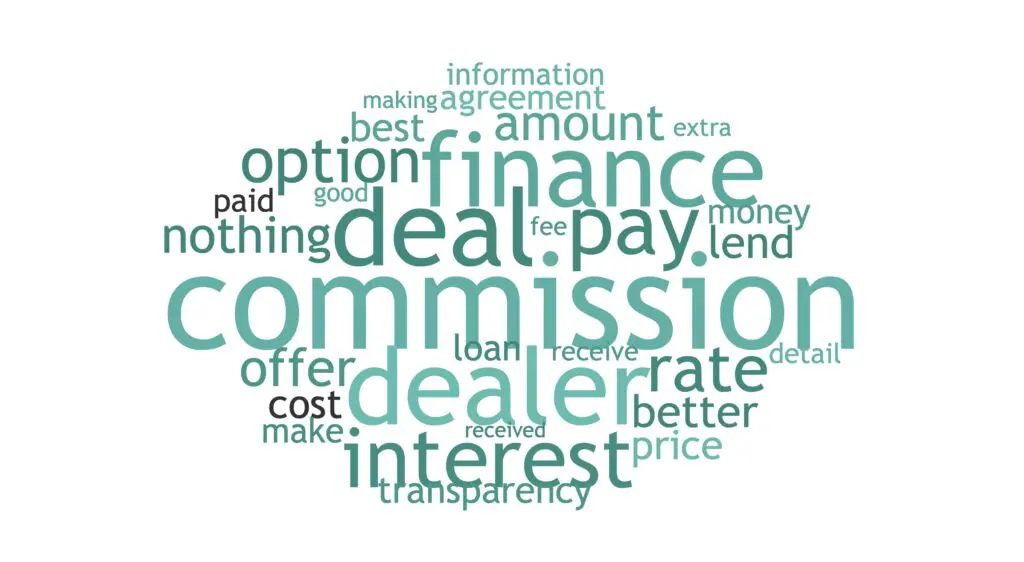
We asked these car finance customers to tell us what they would have liked to know at the time of entering into their loan agreements. Transparency was an important theme in enabling informed decisions. This is something we heard over and over again.
One car finance customer said: ‘They need to be completely transparent on their business practices and provide all the information on their arrangements with lenders so an informed decision can be made.’
Understanding the impact on costs was also key. ‘I would have liked to know that car dealers often receive a commission from finance lenders, as this could impact the overall cost of the vehicle,’ said another respondent to our survey.
This person added: ‘Understanding this could help in negotiating better terms or being more aware of potential hidden costs associated with the financing agreement. Transparency about these commissions would have allowed for a more informed decision when choosing a finance option.’
Others talked about how transparency on how the deal was structured would help build trust in the relationship they had with the dealer. With one person stressing the importance of ‘total transparency’ saying: ‘ I would have trusted that they were offering me the best option available. I wouldn’t have been always wondering if I’d been ripped off.’
And many more talked about the importance of how understanding the exact amount of commission the car dealer received would help them assess whether they were getting the best possible deal or if the dealer had, as one person said, ‘an incentive to push a more expensive financing option rather than one that was in my best interest.’
Key themes in what people would have liked to be told when entering into car finance agreements (1,925 responses)
Better information to help people compare the market
This is a market where many people – who on the whole were pretty savvy when it came to shopping around for other financial products like home and car insurance and other banking services – felt that more was needed to help them compare the market.
Half of respondents (50%) said they wanted their dealers to offer them a choice of car finance deals to consider. One person said they ‘would have liked to see the interest rates on offer from other lenders, as well as any commission being paid to the seller.’
Another respondent said: ‘I would like to know who I’m borrowing the finance from and whether the car dealership has searched the market to offer me the cheapest loan available to them, and whether they receive commission on the loan.’
For others, they simply wanted to be confident that their dealer was offering them the best deal from their panel of lenders – which was seen as one of the most important factors by 49% of respondents. As one person simply put it: ‘I would have liked to know it was the best deal I could get.’
Car finance compensation: Don’t wait, act now!
The regulator has made it clear that it thinks a redress scheme will be simpler for consumers than filing individual complaints. Though you will still be able to take your claim via the courts.
So it’s important that you’re not left in the dark if you suspect you were not informed about the commission fee – and, as a result, may have been overcharged for your car finance.
Contact your dealer or lender to check if your deal involves a commission arrangement. Acting now could help ensure you’re not left out of pocket.
Use our free template letter to help you make your complaint to your lender or read our guide for more advice.
Compensation claim letter
Download our free letter template for claiming back compensation for mis-sold car finance.
Register now for our free letter template to help you with your car finance complaint.
‘Checking is easy’, says one Consumer Voice supporter
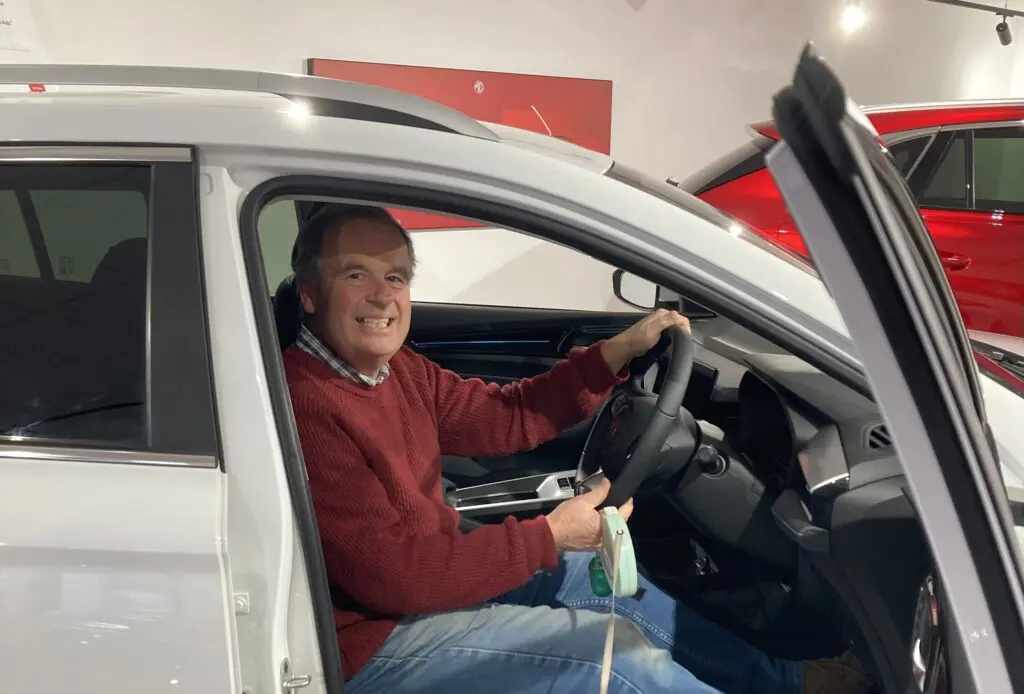
Clive Stainton from the Forest of Dean got in touch with Consumer Voice when we first started reporting on this scandal in early 2024. He, his wife and his daughters have had a number of car finance agreements arranged by his dealership.
While he was keen to stress he has a good relationship with his dealer, he also expressed shock that the market was able to ‘get away with this sort of practice.’
So Clive diligently set about the task of trying to find out whether he’d been affected by discretionary commissions, and he taught us a thing or two in the process.
The financial regulator estimated that 99% of 32 million motor finance agreements entered into since 2007 involved the payment of commission to credit brokers (your car dealers).
Clive said that while ‘remembering back that far is not easy, I used old bank statements to trigger my memory and start the process of identifying which lenders I needed to contact.’
Once he had his list of lenders, he then used our template letter to check whether any of his loans involved discretionary commission. A process he found easy to do once he had all other details of past loans in one place.
We checked in with Clive a year into the process and he told us ‘it’s all coming along nicely thanks to you guys.’ Thanks Clive!
He’s had a response from all ten lenders he’s been in touch with: ‘All have responded to say either they will be dealing with it later in the year or confirming right now that there were discretionary commissions of which I was unaware.’
He’s now waiting for their final responses. He has also been very much in the driving seat when asking lenders who say discretionary commission wasn’t involved whether another type of commission was.
Commenting on one lender in particular, he said: ‘I’m still in correspondence with one lender because they don’t seem to understand that the recent ruling broadened the potential scope of my complaint to them.’
For another ‘less cooperative’ lender he said that ‘they are claiming it’s down to individual dealers to deal with discretionary commission and other commission paid information’. Thankfully Clive is well versed on the topic and knows to tell them this is not the case.
It’s great to know that our supporters are helping to educate the lenders on what they should be doing. Although a cause for concern on the ability of lenders to follow the basic complaint handling rules set out by the regulator.
Thank you Clive for telling us how you got on. And we’d love to hear from more of you about your experiences.
Consumer Voice research
We conducted an online survey of 2,042 UK adults who had taken out car finance loans arranged by their car dealership.
People responding to the survey had taken loans between 1 April 2014 and 28 January 2021, which is when the ban on discretionary commission arrangements came into force. The survey was conducted between 14 and 22 February 2025.
Next week, ahead of the Supreme Court hearing, we will reveal more about the different types of commission arrangements dealers have with lenders and what people think about them.
Consumer Voice is free use, independent and we tell consumers when the companies they buy from have broken the law. We help people easily work out whether they’re entitled to compensation and how to claim.
Sign up to our newsletter to stay updated on claims that could leave you owed compensation.
Related claims
-
Apple Pay
Apple sued over Apple Pay practices that allegedly pushed up banking charges for 50 million consumers.
-
Apple Pay Claim Team
Apple faces collective legal action over unfair charges borne by UK consumers using Apple Pay. This action is led by a consumer rights campaigner and one of the UK’s top group litigation law firms.
-
Apple Pay Claim FAQs
Find answers to common questions about the Apple Pay consumer claim, including eligibility, opt-out rights, funding, costs, and how collective actions work.