Your rights when buying a new or used car, and when you’re entitled to a refund or compensation.
Last updated on 3 August 2026
In this guide…
What you need to know about your rights when buying cars
Your rights when buying from a car dealer
You have certain consumer rights when you buy a new or a used car from a dealer. The Consumer Rights Act 2015 stipulates that your car must be of satisfactory quality, fit for purpose and as described.
What does this mean?
- Satisfactory quality Your car must be in a good condition appropriate to its age and price. New cars should be free from defects, while used cars may have minor cosmetic imperfections that don’t affect functionality. Serious cosmetic damage (large dents, scratches, mismatched paint) or any functional faults (mechanical, electrical or safety issues) count as unsatisfactory quality.
- As described Your car should match the description given or shown to you at the time of purchase.
Fit for purpose You should be able to use your car for the purposes it was advertised or described, and it should last a reasonable amount of time.
How to fix problems with your car: refunds, repairs & replacements
You have a number of rights if your car is of unsatisfactory quality, not as described or unfit for purpose:
- Up to 30 days: You have a short-term right to reject your car from the date it is delivered to you if you find any damage or faults
- Up to 6 months: You can get a full or partial refund if your car can’t be repaired or replaced. The seller has one opportunity to repair or replace your faulty car
- Up to 6 years: You may be entitled to some money back if your car develops a fault. In the first 6 months, it’s assumed the fault was present at purchase (the dealer must prove otherwise). After 6 months, you must prove the fault existed when you bought the car – expert evidence may be needed.
There are exceptions to these rights. You won’t be entitled to a refund, repair or replacement if you caused the damage to your car through misuse or accident, or if you knew about any problems before you bought the car.
If you inspected a used car before buying and failed to notice obvious visible defects (like dents or scratches), you cannot later claim for those specific defects. However, you still have rights for hidden faults or issues that weren’t obvious during inspection.
You won’t be entitled to a refund or repair for ‘fair wear and tear’ – normal deterioration appropriate to the car’s age and mileage, such as worn brake pads on a high-mileage vehicle. However, if wear is excessive for the car’s age and mileage, or if the seller didn’t disclose it, you may still have a claim.
14-day cooling off period for cars bought online
You have extra rights if you buy a car from a dealer online.
You get an automatic 14-day cooling-off period if you haven’t seen the car in person. This starts from the day after receiving your car and applies even if there are no faults. You can simply change your mind and get a full refund.
You have 14-days to return the car once you’ve told the dealer that you’ve changed your mind. You may have to cover the costs associated with doing this. The dealer should have told you about your right to return the car and who would cover the costs when you bought the car online.
Special considerations for electric and hybrid vehicles
When buying an electric or hybrid vehicle, your consumer rights are the same, but there are additional factors to consider:
Battery health and warranty: Check the battery warranty separately from the vehicle warranty. EV batteries typically have 8-year/100,000-mile warranties, but this varies by manufacturer. A degraded battery may count as a fault if it’s worse than expected for the vehicle’s age.
Charging equipment: If charging cables or home charging points are included in the sale, they must also be of satisfactory quality and fit for purpose. If they’re faulty, you have the same rights to replacement or refund.
Range discrepancies: If the advertised range differs significantly from what you experience, this may count as “not as described.” However, range naturally varies with driving conditions, so minor differences may be considered normal.
Software issues: Software faults that affect the vehicle’s functionality are covered under your consumer rights, just like mechanical faults.
Your rights when buying from a private seller
You have fewer rights when you buy a car from a private seller or car auction than when you buy from a dealer.
Cars must not be misrepresented by the seller – so you will typically have the right to a refund or compensation if your car doesn’t match the description advertised. However, it is your responsibility to make sure the car is of satisfactory quality, fit for purpose or free from fault.
If you bought your car from an online marketplace, most will have codes of conduct in place but, legally, they are mostly exempt from liability unless they’re aware, for example, of illegal or stolen goods being sold.
If you have any problems getting your money back from a private seller on an online marketplace then do raise a complaint. See also Tips on getting refunds and putting problems right.
Buying a car on finance?
Download our FREE guide to getting the best car finance deal.
Your car finance rights
You can also find out more about your rights to compensation if you have been mis-sold a car finance loan and how to make a car finance claim in our guide to car finance.
Tips on getting refunds and putting problems right
Contact the dealer first
- Contact the dealer as soon as you spot the problem – this is who your rights are with, not the car manufacturer.
- Explain the problem and be clear on whether you want a refund, repair or replacement. Be polite and stick to the facts. It helps to make reference to your legal rights.
- Keep a record of all your conversations and ask for verbal agreements in writing.
- If you don’t get what you want, file a formal complaint with the dealer.
Protect your rights by keeping these documents safe:
- Sales contract or invoice: Proves what you paid and when
- Vehicle description: Any advertisements, brochures or dealer descriptions
- Finance agreements: If you bought on finance
- Warranty documents: Separate from your consumer rights
- Service history: Shows the car’s condition at purchase
- MOT certificates: Required for cars over 3 years old
- V5C registration document: Proves ownership (though the seller may send this directly to DVLA)
Take photos or videos of the car when you collect it and document its condition.
Getting your money back from your bank or credit card company
There are other ways you can solve your problem if speaking to the dealer doesn’t work or they ignore your complaint
- If you paid by credit card (even just a deposit), you can claim under Section 75 of the Consumer Credit Act 1974 for cars costing between £100 and £30,000. Your card provider is jointly liable with the dealer, giving you extra protection. Speak to your credit card company to do this.
- If you paid by debit card, you can ask for your money back using ‘chargeback’ which is a way for your card provider (including credit cards) to claim money from your retailer’s bank. You have 120 days from the transaction processing date and will need evidence that there has been a breach of contract.
Returning a car you part-exchanged for
If you reject a car and part-exchanged your old vehicle:
- You’re entitled to get your old car back or receive its agreed value
- If the dealer has already sold your old car, they must pay you its part-exchange value
- If they’ve not sold it but it’s been damaged or depreciated, they must still return it in the condition it was when you handed it over
If the dealer goes out of business
If the dealer closes down or becomes insolvent before resolving your complaint:
- Credit card (£100-£30,000): Use Section 75 – your card provider is still liable
- Debit card: Try chargeback, but success is less certain as the dealer’s bank account may be frozen
- Cash payment: You’ll need to register as a creditor in the insolvency proceedings, but you’re unlikely to get much money back
- Finance: Contact your finance provider – they may have obligations depending on your agreement type
This is why paying by credit card offers the strongest protection.
Escalating unresolved complaints
- You may be able to escalate unresolved complaints to The Motor Ombudsman – it helps with disputes against the 7,500 dealers signed up to its Codes of Practice.
- You can escalate your complaint to the Financial Ombudsman Service if you unsuccessfully tried to get your money back using Section 75.
- You can also do this for an unsuccessful ‘chargeback’ claim if your bank won’t appeal to the dealer’s bank. If they have and the appeal fails then there is nothing else you can do.
- As a last resort, you can take a seller to court to claim money you’re owed. This is known as taking someone to a ‘small claims court’ and it will cost you money and time. Fees will vary depending on the value of the claim you’re making.
Getting your deposit back
If you paid a deposit but haven’t taken the delivery:
- Cancelling celling before delivery: Whether you can get your deposit back depends on your contract terms. Some deposits are non-refundable, while others are refundable if you cancel within a certain period.
- Dealer breaches contract: If the dealer fails to deliver the car as described or on time, you can cancel and get your deposit back.
14-day cooling-off period: If you bought online, your deposit is fully refundable within 14 days of the contract being signed (before delivery).
Claiming compensation if your car causes injury or death
Cars you buy must be safe. You are entitled to claim compensation if your car causes injury or death. This applies whether you bought your car from the manufacturer or not.
Dealers and manufacturers (and sometimes others involved in the making of the product) are liable for their products under the Consumer Protection Act 1987. This product liability law gives you the right to sue for damage or injury caused by faulty products.
You have the right to make a personal injury claim if you have been injured by a faulty car. You must claim compensation quickly because there are strict time limits on making claims – for example, negligence claims must be made within three years of injury.
Personal injury claims can be expensive so check to see if your car insurance policy covers legal expenses like these. You might be able to get help using a no-win-no-fee arrangement with your solicitor. If you win, fees will be paid by the company you’re claiming from.
Finding a lawyer with the right experience is important. A good starting point is to look for a solicitor who is a member of a recognised scheme or body. For example:
- The Law Society’s personal injury accreditation scheme – www.lawsociety.org.uk
- The Association of Personal Injury Lawyers – www.apil.org.uk
Claiming compensation if your car is damaged by potholes
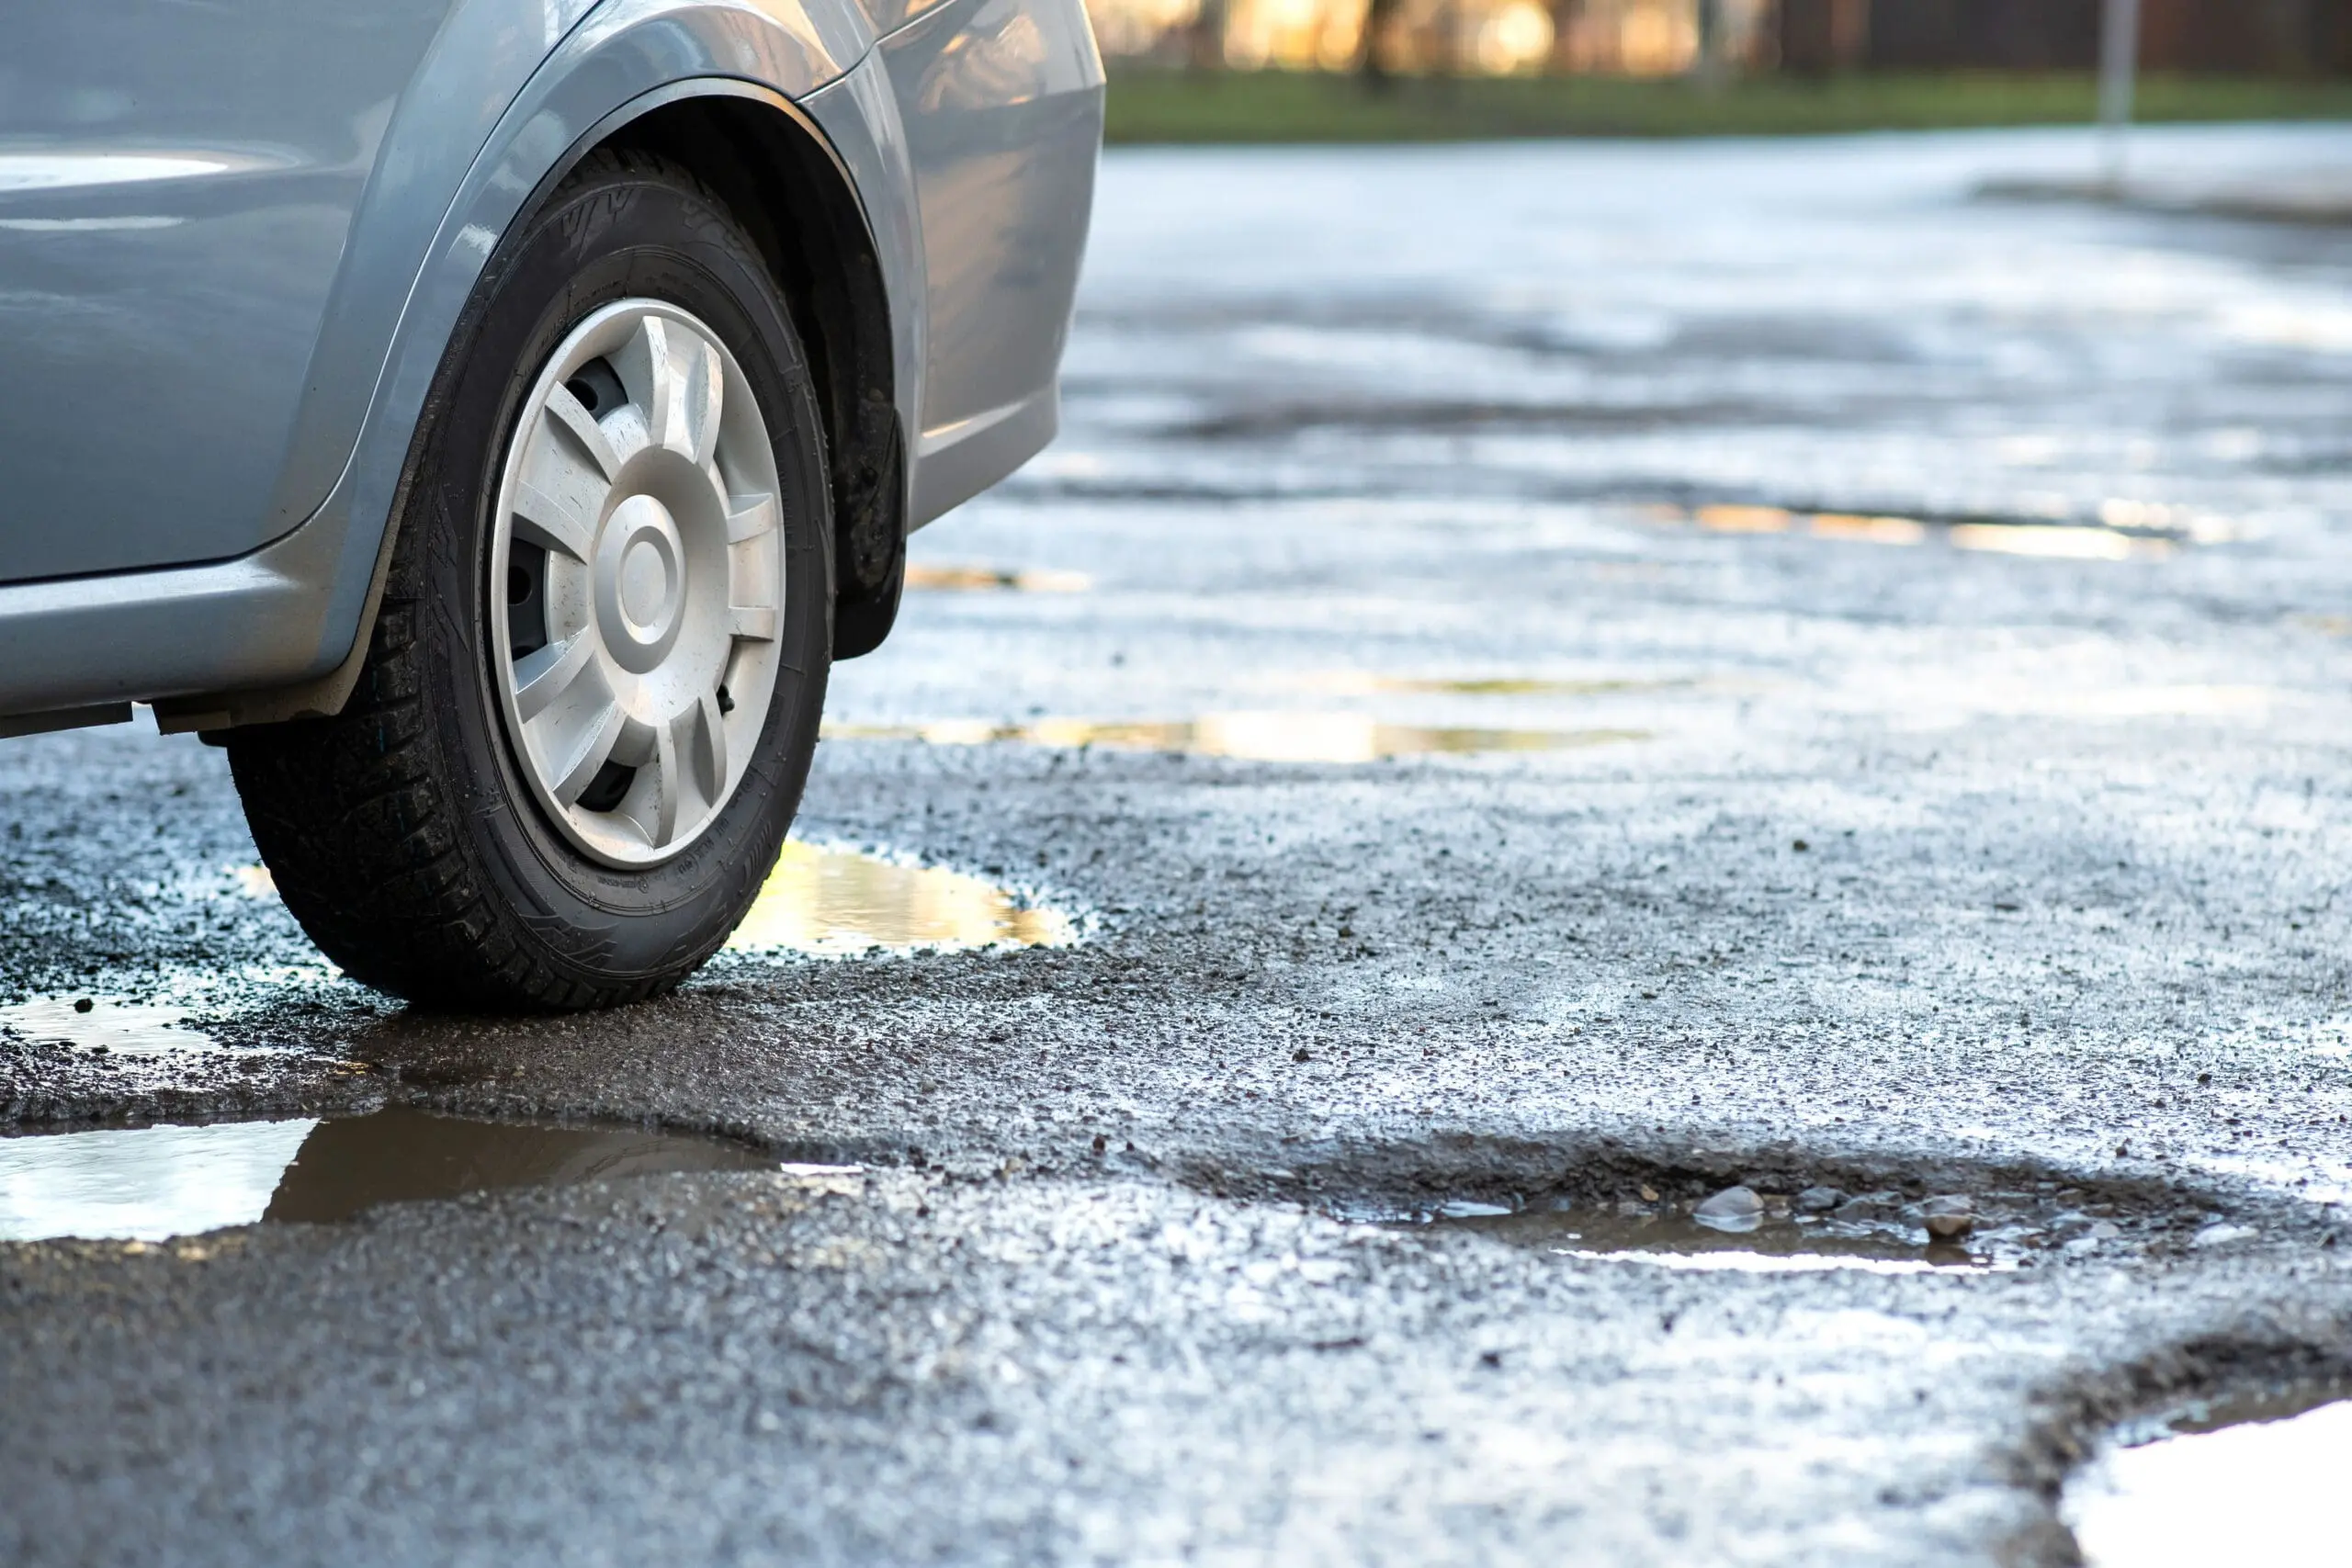
You shouldn’t suffer in silence if your car is damaged by a pothole. You may be able to claim compensation if you’ve hit a pothole in the road and it causes damage to any part of your car. Who you report the problem to and claim compensation from will depend on who manages the road.
Check your local authority’s claim procedure and gather as much evidence as possible to submit a claim. Typically you will need photos of the pothole and the damage caused, along with any estimates or receipts for the repair work.
Most A-roads and motorways are managed by National Highways, many major London roads (known as red routes) are managed by Transport for London and all other roads are typically managed by local councils.
More information on how to report a pothole or claim compensation for damage caused by roads can be found on gov.uk.
Get free advice from the consumer helpline
You can contact Citizens Advice consumer helpline if you need more help dealing with tricky dealers or sellers.
About Consumer Voice
Consumer Voice helps people get back money they may be owed when companies get it wrong. We explain your rights clearly, so you can understand whether you may be owed compensation, whether you can join a claim, and what steps to take next.
Related news
-
Major car finance law firm calls for ban on claims adverts
One of the UK’s biggest car finance claims firms wants advertising stopped to prevent more drivers being signed up twice and facing cancellation fees.
-
Dieselgate drivers face fresh setback in fight for compensation
Another court setback has left 1.6 million diesel emissions claimants facing uncertainty over compensation, but their lawyers aren’t giving up the fight.
-
Car finance compensation: FCA challenge goes to trial in February
The Tribunal has agreed to examine evidence from Consumer Voice’s experts and ordered the FCA to release more data behind its payout calculations.